Is a used car business legal in India? Yes — and the compliance picture splits into two genuinely different categories depending on whether you’re an individual selling your own car occasionally or running a business that buys and resells vehicles regularly. This distinction matters enormously, because one path carries essentially zero regulatory obligation, while the other pulls in GST registration, RTO trade certification, and dedicated tax treatment specific to second-hand goods.
India’s used car market has grown substantially, driven by both traditional dealerships and newer platforms like Cars24 and Spinny bringing structure to what was historically a fairly informal industry. That formalisation has come with real regulatory clarity too, particularly around how GST applies to used vehicles — a set of rules that changed meaningfully as recently as 2025 and is worth understanding precisely before you set pricing or structure your business.
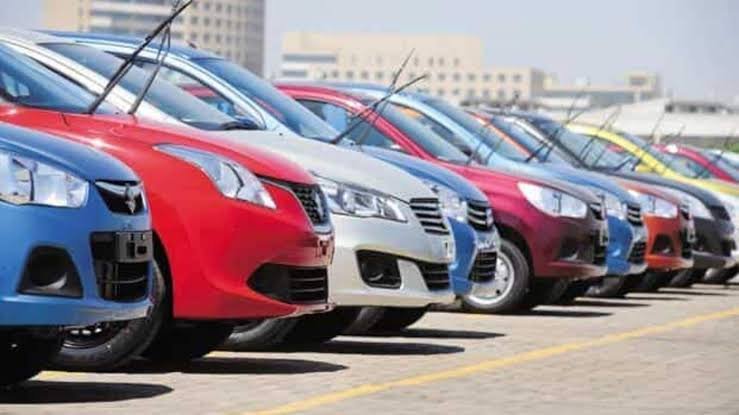
When You’re Completely Outside Any Regulation: Individual Sale
Let’s settle this first, because it genuinely surprises people who assume any vehicle sale involves paperwork and tax. When a private individual sells their personal car to another private person, no GST applies whatsoever, and no dealer registration, trade license, or RTO trade certificate is needed. You pay nothing beyond the standard ownership transfer formalities at the RTO — updating the registration certificate into the buyer’s name and handling insurance transfer.
This applies regardless of how much profit you personally made on the sale, since the transaction isn’t part of a business. If you sell your own used car to a friend or through a classifieds listing, that’s it — you’re outside the entire compliance framework covered below.
What Changes the Moment You’re Running a Business
The moment you’re buying vehicles specifically to resell them — even informally, even at modest scale — you’ve crossed into business territory, and a genuinely different compliance picture applies:
- Business registration — proprietorship, LLP, or private limited company, with a PAN in the business’s name
- Shop and Establishment licence, covering your operating premises from the municipal authority
- Trade licence, also from the municipal authority, specifically permitting your commercial activity at that address — worth confirming parking, signage, and zoning compliance before signing a lease, since these local rules can create real friction later if not checked upfront
- RTO dealer registration, generally required for anyone operating as a motor vehicle dealer, distinct from and in addition to the trade certificate covered below
The RTO Trade Certificate: Often Confused With the Trade License
This is genuinely one of the most commonly mixed-up requirements in this space, and it’s worth being precise about the distinction. The trade licence covers operating your commercial premises, issued by the municipal authority. The RTO trade certificate is a completely different thing — issued under Rules 33 to 38 of the Central Motor Vehicles Rules, 1989, and specifically relevant if you’ll be moving vehicles that aren’t registered to you.
- A trade certificate comes with trade plates, allowing you to legally drive an unregistered or not-yet-transferred vehicle — essential for a dealer moving inventory between locations, to and from customers, or for test drives
- State practice for used-vehicle dealers specifically varies, so confirm directly with your local RTO whether your specific operation needs this, rather than assuming a uniform national requirement
GST and the Margin Scheme: The Tax Mechanic Every Dealer Needs to Get Right
This is the part with the most genuine nuance, and getting it wrong on your very first invoice creates a compliance trail that’s hard to unwind later.
Under Rule 32(5) of the CGST Rules, 2017, registered dealers selling used vehicles without having claimed input tax credit on the purchase can use the margin scheme — GST is charged only on the margin (selling price minus purchase price), not on the full transaction value. This is a considerably lighter tax burden than taxing the entire sale amount, and it’s specifically what makes formal used-car dealing viable at reasonable margins.
Key mechanics worth understanding clearly:
- The unified rate is 18% GST on the margin, in effect since 16 January 2025 and left unchanged by the broader GST 2.0 reform in September 2025 — this replaced a previous range of 5% to 28% that varied by vehicle type and age
- If a vehicle is sold at a loss — selling price below purchase price — no GST is payable on that transaction at all
- ITC is allowed on business expenses like repairs, spare parts, rent, advertising, and professional fees, but specifically not on the purchase of the used vehicles themselves under the margin scheme
- GST registration becomes mandatory once your aggregate turnover — which includes margins from margin-scheme sales and full value from other transactions — crosses ₹20 lakh (₹10 lakh in special category states)
- Smaller dealers with turnover up to ₹1.5 crore can evaluate the Composition Scheme for simplified, lower-rate compliance
Get your purchase records organised from day one, since your entire margin scheme tax liability depends directly on being able to document what you actually paid for each vehicle — a gap in purchase documentation turns a lighter margin-based tax bill into a much larger liability calculated on full value instead.
TCS on High-Value Sales
A detail worth knowing if your inventory includes higher-value vehicles: under Section 206C(1F), dealers must collect 1% Tax Collected at Source on the sale of motor vehicles exceeding ₹10 lakh, calculated on the invoice value including GST. This is a separate compliance obligation from GST itself and applies specifically at that value threshold, so build it into your invoicing process for premium inventory.
The Anti-Theft Angle: Purchase and Sale Registers
This is a genuinely distinctive requirement worth knowing, since it doesn’t come up in most other business categories covered in this series. Several jurisdictions require second-hand dealers specifically to maintain purchase and sale registers that remain open to police or municipal inspection — a compliance measure aimed squarely at preventing stolen vehicle trafficking through legitimate-looking dealerships.
Check what specifically applies in your state and municipality, but treat maintaining organised, inspectable purchase records as standard practice regardless of whether it’s explicitly mandated locally — it protects your business reputation as much as it satisfies any regulatory check.
Per-Sale Paperwork That Protects Both You and Your Buyer
Beyond the registration layer, each individual sale carries its own documentation trail worth building into a consistent process:
- Forms 29 and 30 filed for ownership transfer, plus a Form 28 NOC where the sale involves an inter-state move
- Margin scheme GST invoice, correctly showing registration number, HSN code, GSTIN, taxable margin, and full tax break-up
- RC verification, confirming the registration certificate physically matches the chassis and engine numbers on the vehicle — a basic but essential fraud-prevention check before any purchase
- Insurance transfer initiated promptly in the buyer’s name
- Delivery note with buyer KYC, capturing date, time, odometer reading, and vehicle condition at handover — genuinely useful protection if a dispute arises later
What Happens If You Skip Proper Registration
The consequences scale with which specific compliance gap you’re carrying:
- Operating as a de facto dealer — buying and reselling regularly — without proper business registration and GST compliance exposes you to interest, penalties, and potential prosecution once your activity is identified as commercial rather than personal
- Missing the RTO trade certificate while moving unregistered vehicles as inventory risks fines and complications if stopped, since driving a vehicle not registered to you without proper authorisation is itself a violation
- Incorrect GST treatment — taxing full sale value instead of margin, or vice versa without eligibility — creates compliance exposure that’s genuinely harder to unwind the longer it continues
- Poor purchase documentation undermines your ability to use the margin scheme correctly, potentially forcing you into full-value taxation retroactively if records can’t substantiate your original purchase price
FAQs
Q1. I occasionally buy a used car, fix it up, and resell it for profit — am I considered a business under this framework?
If this becomes a regular pattern rather than a one-off personal sale, yes, you’re likely operating as a business and should register accordingly. Occasional, genuinely personal transactions stay outside this framework, but repeated buy-resell activity crosses into dealer territory.
Q2. Do I need both a trade licence and an RTO trade certificate, or is one sufficient?
Generally both are relevant but for different purposes — the trade licence covers your commercial premises, while the RTO trade certificate specifically authorises moving vehicles not yet registered to you. Confirm with your local RTO whether your specific operation needs the latter.
Q3. If I sell a used car at a loss, do I still need to file a GST return for that transaction?
Yes, registered dealers still need to report the transaction even though no GST is payable when sold at a loss under the margin scheme. The filing obligation continues regardless of whether tax is actually due on that specific sale.
Q4. How do I protect myself from accidentally buying and reselling a stolen vehicle?
Verify the RC matches the physical chassis and engine numbers before purchase, maintain organised purchase records open to inspection, and check the vehicle’s hypothecation and ownership history through the RTO before completing any transaction.